Retirement income planning
Turn savings into a paycheck. A dynamic income strategy that adjusts to markets, tax law, and life, so you can spend with confidence.
Our approach
Every client follows the same five-step process—the Summit Ascent Pathway—but the trail through it is yours. Here is how the two fit together, what we coordinate, and what to expect along the way.
The Summit Ascent Pathway
Five stages, in order. The first two are about deciding whether we’re the right fit; the last three are the work we do together once you engage us.
A conversation about your goals, concerns, and what matters most—so we can both decide whether we’re the right fit.
We test your current plan against markets, taxes, healthcare costs, and a long life to find opportunities and tradeoffs.
Once you engage us, we build your income, investment, tax, and protection strategy as one written plan.
We put the plan into action—accounts, withdrawals, tax moves, protections—coordinated with your CPA and attorney.
We review, adjust, and keep you informed as markets, tax law, and life change.
What you’ll experience
The Pathway is the same for everyone. Here is what each stage looks and feels like from your side of the table.
A conversation, not a presentation. You tell us what matters most in your retirement and what concerns you, and together we look for risks you may not have been aware of yet.
From there, we share more about our planning process and philosophy. If it feels like a fit, we invite you back for your Stress Test.
*Estimates are fine. Documents aren’t needed until the Stress Test.
We send a secure way to share recent statements: investment and retirement accounts, Social Security estimates, any pension, insurance policies, and your most recent tax return. Never through ordinary email.
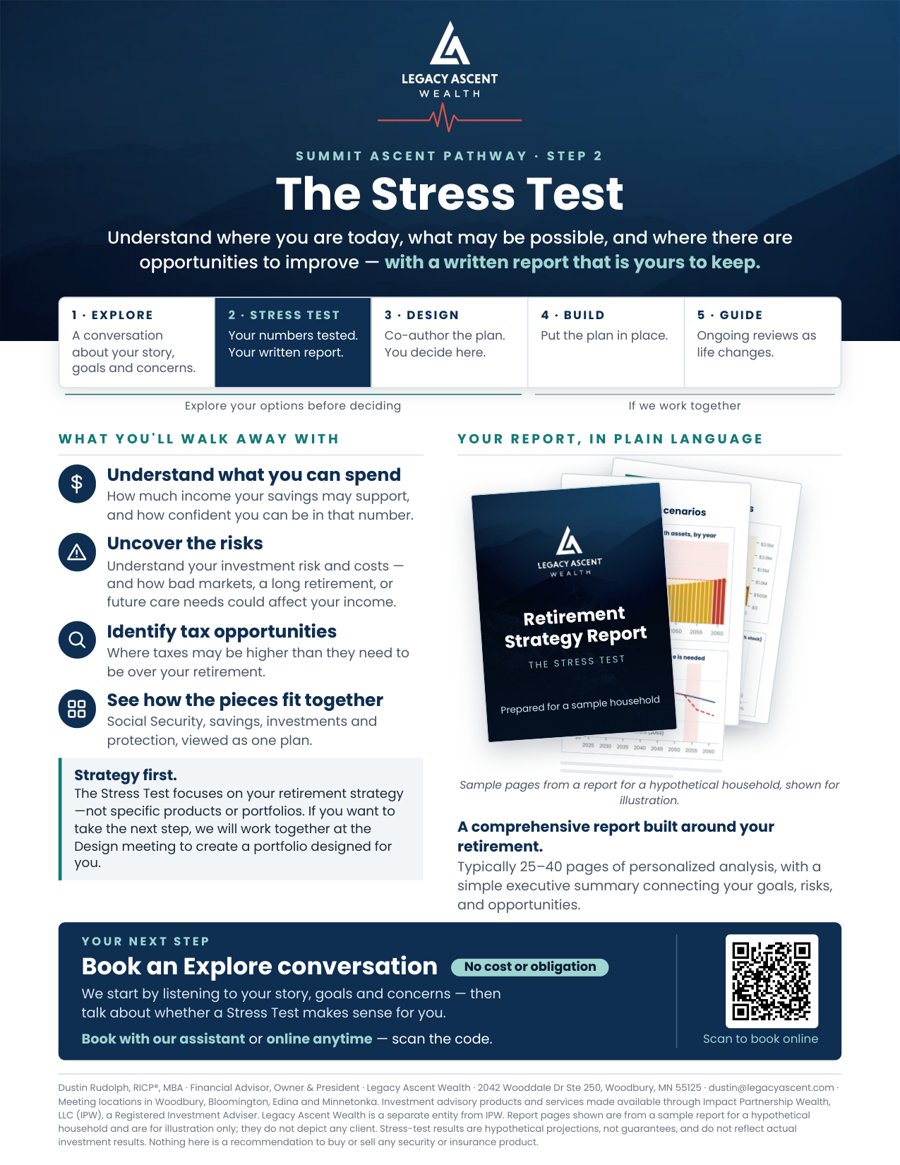
We walk through your written report together: typically 25–40 pages with a plain-language executive summary. You see what is working, where the blind spots are, and which decisions deserve attention. Strategy only, no product recommendations. Then you decide whether to move forward.
How your income holds up
We run your plan through many market paths, not one average, to see when spending holds and when it doesn’t.
Your findings, at a glance
Each area gets a plain-language finding and the decisions that deserve attention.
We build your strategy with you, not for you. You see the options, the tradeoffs, and the reasoning before anything is decided.
Example: how a retirement paycheck is layered
In Design we decide which accounts fund each layer, and how the order changes your taxes and Medicare costs over time.
You leave with a written plan you understand and could explain to your family.
We put the plan into action: open accounts at Fidelity, coordinate transfers, set up your income, and carry out the agreed tax moves, working with your CPA and attorney.
Retirement is not set-and-forget. Markets move, tax law changes, and life happens. Guidance is where the plan earns its keep.
We set this year’s paycheck: withdrawals, RMDs, and Social Security, coordinated with your CPA for tax season.
Client education · What changed this yearProgress, spending, and any changes in your life or goals.
Client eventOne topic in depth: Medicare, long-term care, estate and beneficiaries, or giving.
Client eventRoth conversion, RMD, and charitable decisions before December 31.
Client education · Year-end planningSummit Ascent Pathway · Step 2
What you'll walk away with, what the written report looks like, and where it fits in the process, all on one page.
Report pages shown are from a sample report for a hypothetical household. Stress-test results are hypothetical projections, not guarantees.
Why coordination matters
Take one ordinary choice—withdrawing money from your portfolio. It changes which assets you sell, your income this year, the taxes you owe, what you pay for Medicare, and what remains for later. We plan for all five together, so one good decision doesn’t quietly create three problems.
Comprehensive retirement planning
Seven pieces. One plan. The question is whether they’re working together.
Minnesota rules are shown. Each state treats retirement income, Social Security and estates differently. General educational information, not tax or legal advice. Rules reflect current law and can change, and your situation may differ.
Your planning lens
The process is the same for everyone. The trail is not. Many paths lead in the right general direction—only one is right for you. These five questions decide it.
Roth conversions, RMDs, IRMAA, and lifetime tax planning—not just this year’s return.
Are your investments optimized for the risk you’re taking—and aligned with your goals?
Assets, income, taxes, and estate decisions aligned to one plan—so no piece works against another.
Social Security, pensions, and withdrawals combined into one dependable paycheck.
Survivor needs, long-term care, and beneficiaries, coordinated with your attorney.
What we coordinate
These are not separate services you buy à la carte. They are the parts of one coordinated plan.
Turn savings into a paycheck. A dynamic income strategy that adjusts to markets, tax law, and life, so you can spend with confidence.
Coordinated planning around Roth conversions, Social Security timing, RMDs, and withdrawal sequencing—designed to keep more of your money working for you.
A strategic portfolio approach that balances growth, risk, and flexibility, built around your timeline and income needs. Accounts are custodied at Fidelity.
Where appropriate, fixed insurance solutions for guaranteed income, long-term care, and survivor protection.
Beneficiary design, charitable giving, and intergenerational strategies, coordinated with your attorney and CPA. We don’t draft documents; we make sure the plan works as intended.
Scheduled reviews, quarterly touchpoints, and adjustments as life, markets, and tax law change.
What to expect
New clients typically meet with us three to four times in the first 60–90 days to build the plan and complete the key implementation steps. After that, we provide quarterly touchpoints and meet at least twice a year.
Explore, Stress Test, and Design meetings. Your written plan takes shape and the first implementation steps are completed.
A touchpoint on what changed—markets, tax law, your life—and whether anything in the plan should move.
A full review meeting: income, taxes for the year ahead, portfolio, protection, and estate coordination.
Fit
People who want income, taxes, investments, and legacy decisions working together, who value clear explanations, and who want to understand their options.
If you’re looking for someone to trade actively, or for the lowest-cost advice with no ongoing coordination, we’re likely not the right firm—and we’ll tell you so in the first meeting.
Take the first step
A complimentary Explore meeting is the easiest way to see if we’re the right fit—no cost, no obligation. We’ll talk about where you are, what you’re hoping for, and what a clearer plan could look like.
A conversation, not a presentation. You tell us what matters most in your retirement and what concerns you, and together we look for risks you may not have been aware of yet.
From there, we share more about our planning process and philosophy. If it feels like a fit, we invite you back for your Stress Test.
*Estimates are fine. Documents aren’t needed until the Stress Test.
We send a secure way to share recent statements: investment and retirement accounts, Social Security estimates, any pension, insurance policies, and your most recent tax return. Never through ordinary email.
We walk through your written report together: typically 25–40 pages with a plain-language executive summary. You see what is working, where the blind spots are, and which decisions deserve attention. Strategy only, no product recommendations. Then you decide whether to move forward.
How your income holds up
We run your plan through many market paths, not one average, to see when spending holds and when it doesn’t.
Your findings, at a glance
Each area gets a plain-language finding and the decisions that deserve attention.
We build your strategy with you, not for you. You see the options, the tradeoffs, and the reasoning before anything is decided.
Example: how a retirement paycheck is layered
In Design we decide which accounts fund each layer, and how the order changes your taxes and Medicare costs over time.
You leave with a written plan you understand and could explain to your family.
We put the plan into action: open accounts at Fidelity, coordinate transfers, set up your income, and carry out the agreed tax moves, working with your CPA and attorney.
Retirement is not set-and-forget. Markets move, tax law changes, and life happens. Guidance is where the plan earns its keep.
We set this year’s paycheck: withdrawals, RMDs, and Social Security, coordinated with your CPA for tax season.
Client education · What changed this yearProgress, spending, and any changes in your life or goals.
Client eventOne topic in depth: Medicare, long-term care, estate and beneficiaries, or giving.
Client eventRoth conversion, RMD, and charitable decisions before December 31.
Client education · Year-end planningSchedule a conversation
Both are complimentary. No cost, no obligation.